Helping your teen to manage their first paycheck responsibly
Your teenager has just landed their first job, and you’re probably feeling super proud and maybe a bit nervous, too. They’re becoming independent, and how they handle their first earnings could shape their money habits forever.
As parents, we witness this pivotal moment with mixed emotions. That part-time job at the local cafe, weekend shifts at the retail store, or summer position at the leisure centre represents more than just pocket money. It’s the beginning of their financial journey. Research from the Money and Pensions Service shows that money habits formed between ages 16-18 typically persist into adulthood1, making this period crucial for kids learning how to manage their money.
Building essential life skills early
That first paycheck represents so much more than cash in hand. It’s freedom, responsibility, and a chance to mess up or get things brilliantly right. This is where you come in.
Teaching money management now isn’t about being the fun police. It’s about giving your teen tools they’ll actually use. Parents and carers working with Foster Care Associates both face this challenge, though foster children might need extra support since they often transition to independence more abruptly than their peers. Either way, your guidance matters enormously.
The gap in financial education
Money skills aren’t taught properly in schools, so your teen needs to learn through real experience. Their weekend job provides the perfect training ground since it’s low stakes but has real consequences.
Despite financial literacy being added to the national curriculum, a 2024 study by the London Institute of Banking & Finance found that 82% of young people want to learn more about money and finance in school2. 69% of young people now say they have access to financial education in school, compared to 29% in 20153
This is great, but there’s still an education gap that parents, particularly mothers who often handle day-to-day household budgeting, fill when they become the primary financial educators. So, your teenager’s first job offers an unparalleled opportunity to bridge this gap with practical, hands-on learning that sticks.
Understanding your teen’s financial psychology
Teenagers process money differently from adults. Their prefrontal cortex, responsible for long-term planning and impulse control, won’t fully develop until their mid-twenties. This biological reality means they’re naturally inclined toward immediate gratification rather than future planning, so understanding this helps us approach financial education with patience and realistic expectations.
When your teenager receives that first paycheck, their brain releases dopamine, the same reward chemical triggered by social media likes or video game achievements. This creates a powerful emotional connection to earning money, which we can harness for positive financial learning. We can guide them through this experience thoughtfully, to help them wire their brains for better financial decision-making.
The unique position of parents as financial mentors
Working parents bring their own unique perspectives to teaching financial literacy. We understand the juggling act of managing household finances, the reality of making every pound stretch, and the importance of financial independence. Statistics show that 55% of women living with a partner say they have the most responsibility for day-to-day budgeting4, making us naturally positioned to pass on practical money wisdom.
It is important to share your own experiences, as the financial mistakes you made at their age are lessons you learned the hard way, and the strategies you developed have served you well. The transparency with your child also builds trust and makes financial conversations feel less like lectures and more like valuable life advice from someone who’s been there.
Creating smart spending habits
Of course, your teenager may want to blow their entire paycheck on clothes or games – who wouldn’t! The trick isn’t stopping them completely but helping them think it through first.
Try suggesting they split their money into thirds: some for immediate wants, some for bigger goals, and some for saving. Try not to be too rigid with percentages; flexibility keeps them engaged. Let them choose what matters to them.
Watch what happens when they really want something expensive. Do they wait and save, or do they impulse buy and regret it later? These moments teach far more than any lecture ever could.
The three-jar method modernised
While the traditional three-jar method (spending, saving, giving) remains valuable, today’s teens need a digital-age approach. Consider introducing a modified system that reflects modern financial realities:
Jar 1: Immediate enjoyment (40-50%)
This isn’t just frivolous spending–it’s learning to enjoy the fruits of their labour responsibly. Whether it’s grabbing coffee with friends, downloading music, or buying that trendy jumper, this spending teaches them to value their work and make conscious choices about immediate pleasures.
Jar 2: Short-term goals (25-30%)
This might include saving for festival tickets, a new phone, driving lessons, or university freshers’ week. These goals, typically achievable within 3-6 months, teach the satisfaction of delayed gratification without the frustration of endless waiting.
Jar 3: Future fund (20-30%)
This is their long-term savings – university expenses, a gap year, or simply an emergency fund. Even small amounts accumulate significantly over time, and seeing this growth builds confidence in their ability to prepare for the future.
Teaching value vs price
One crucial lesson often overlooked is helping teenagers understand the difference between value and price. That £60 branded hoodie might seem essential to them, but discussing cost-per-wear can shift perspectives. If they’ll wear it twice, that’s £30 per wear. Compare that to a £30 hoodie worn 30 times–just £1 per wear.
Introduce them to concepts like:
- Quality over quantity: Sometimes paying more upfront saves money long-term
- The 24-hour rule: Wait a day before non-essential purchases
- Opportunity cost: What else could that money buy or achieve?
- Social pressure spending: Recognising when they’re buying to fit in rather than from genuine desire
Navigating peer pressure and social spending
Teenagers face immense pressure to keep up with their peers financially. Social media amplifies this with constant exposure to others’ highlight reels. Address this directly by discussing:
- The reality behind social media posts (not everyone is being truthful about affording things)
- The confidence that comes from financial security vs. temporary satisfaction from purchases
- Ways of socialising that don’t require significant spending
- The respect earned from being financially responsible
Research shows that teenagers who understand their spending triggers make better financial decisions. Help your teen identify their vulnerable moments–is it scrolling through social media, shopping with certain friends, or feeling stressed about school?
The power of saving
Saving money as a teenager feels pointless until you see it actually working. Even putting away ten pounds from each paycheck creates momentum. Your teen starts noticing their balance growing. That’s when saving stops feeling like punishment and starts feeling like power.
Help them open their own bank account. Let them speak to the bank staff, ask questions, and make decisions. This ownership makes everything feel more real and less like something adults control.
Many teenagers save for driving lessons or university. Others want festival tickets or designer trainers. The goal matters less than developing the habit of consistently setting aside money.
Making saving tangible and rewarding
The abstract nature of saving challenges teenagers who live in an instant-gratification world. Make it concrete by:
Creating visual progress trackers
Whether it’s a savings thermometer on their bedroom wall or a digital tracker app, a visual representation makes progress real. Seeing that the driving lessons fund grows from £0 to £500 to £1,000 provides continuous motivation.
Establishing milestone rewards
Celebrate savings milestones without undermining the lesson. When they save their first £100, perhaps contribute an extra £10. This reinforces positive behaviour without removing their responsibility.
Introducing the compound effect
Show them how money grows over time. If they save £50 monthly from age 16, they’ll have £2,400 by 20 without interest. Add compound interest, and it’s even more. Use online calculators to demonstrate how starting early magnifies results.
Different savings strategies for different personalities
Not every teenager responds to the same savings approach. Identify your teen’s money personality:
- The Competitive Saver – Challenge them to savings competitions with siblings or friends
- The Goal-Oriented Saver – Help them set specific, measurable targets with deadlines
- The Spontaneous Saver – Suggest automatic transfers so saving happens without thinking
- The Visual Saver – Provide charts, graphs, and apps that show progress clearly
Building emergency fund awareness
While “emergency fund” sounds boring to teenagers, reframe it as their “freedom fund” or “opportunity fund.” This money means they can:
- Handle unexpected costs without asking parents
- Take advantage of sudden opportunities (last-minute concert tickets when a friend can’t go)
- Feel secure knowing they’re prepared for surprises
- Experience the adult satisfaction of solving their own problems
Start small. Even £50 set aside provides a cushion and builds the emergency fund habit.
Teaching real-world money management
Your teen’s payslip may confuse them at first. Why is their take-home pay less than their hourly rate multiplied by hours worked? This is a perfect opportunity for a reality check about taxes and National Insurance.
Don’t just explain deductions. Show them where that money goes. Talk about NHS funding, road maintenance, and benefit systems. Suddenly, taxes feel less like theft and more like membership fees for living in society.
Share some household costs too. When your teenager discovers how much the weekly shop costs or what you pay for electricity, they gain perspective on the financial pressures of adulthood. Foster carers might find this particularly important since foster children often face these realities sooner than expected.
Decoding the payslip together
That first payslip provides numerous teaching opportunities. Sit down together and examine:
Gross pay vs net pay
Explain how their £10/hour for 10 hours doesn’t equal £100 in their pocket. Break down each deduction:
- Income tax (if applicable)
- National Insurance contributions
- Pension contributions (if offered)
- Student loan repayments (for older teens)
Understanding tax codes and allowances
Teach them about personal allowances (£12,570 for 2024/25) and how tax codes work. Many teenagers don’t realise they might be entitled to tax refunds if they work only part of the year.
The importance of keeping records
Encourage them to photograph or file their payslips. This habit serves them throughout their working life and teaches organisational skills that extend beyond finances.
Real household economics
Create teaching moments by involving your teenager in household financial decisions:
The weekly shop challenge
Give them the actual grocery budget and list. Let them plan meals, compare prices, and experience the reality of feeding a family within constraints. They’ll quickly understand why you say no to certain requests.
Utility understanding
Show them utility bills and explain:
- How usage affects costs
- Why you ask them to turn off lights
- The real cost of long showers
- How small actions impact family finances
Create a simplified monthly budget showing:
The true cost of living
- Mortgage/rent: £800-1,500 (depending on area)
- Utilities: £150-200
- Food: £400-600 for a family
- Transport: £200-400
- Insurance: £100-200
- Miscellaneous: £200-300
This reality check helps them understand that their £200 monthly earnings, while exciting, wouldn’t cover even basic living expenses.
Introducing credit and debt concepts
While they can’t access credit cards yet, teenagers need to understand credit before they’re offered it.
The Cost of Borrowing Use relatable examples: “If you borrowed £1,000 for that gaming computer at 20% APR and paid minimum payments, you’d pay £1,200 total and take two years to clear it.”
Building credit history
Explain how their mobile phone contract (if they have one) affects their credit score. Discuss how future landlords, employers, and lenders might check their credit history.
Good debt vs bad debt
Introduce the concept that some debt (student loans, mortgages) can be investments in their future, while other debt (payday loans, excessive credit cards) can trap them financially.
Setting up for success
These early money lessons stick. Your teenager who learns to budget their Saturday job wages finds university finances less overwhelming. They understand debt, interest rates, and delayed gratification because they’ve practised with smaller amounts.
Confidence grows through experience. Each successful saving goal or wise spending decision builds their self-trust. They start believing they can handle bigger financial challenges because they’ve already proven they can handle smaller ones.
Mistakes happen too, and that’s valuable. Better to learn from overspending £20 at 16 than £2000 at 26.
Creating financial milestones and celebrations
Acknowledge your teenager’s financial achievements to reinforce positive behaviours:
First month success
When they successfully manage their first full month’s pay, celebrate this achievement. Perhaps have a special dinner where they contribute by buying dessert – letting them experience the joy of treating others.
Six-month review
After six months of working, conduct a friendly “financial review.” Discuss:
The one-year mark
This significant milestone deserves recognition. Consider creating a “financial achievement certificate” or letting them make a larger purchase they’ve saved for. Reflect on how much they’ve learned and grown.
Preparing for university and beyond
Your teenager’s part-time job experience provides perfect preparation for university financial challenges:
Student loan literacy
Explain how student loans work differently from other debt. Discuss:
- Repayment thresholds
- Interest rates
- The reality of graduate starting salaries
- Budgeting for university life
The part-time work balance
Share strategies for balancing work and studies. Many successful students work 10-15 hours weekly during term time, using earnings for socialising and extras while loans cover essentials.
Post-university planning
Help them understand the financial transition from student to graduate:
- Typical graduate salaries in their field of interest
- The reality of London living costs vs other cities
- How to budget on an entry-level salary
- The importance of continued saving habits
Technology and financial management
Today’s teenagers have powerful financial tools at their fingertips. Guide them toward helpful resources:
Recommended apps for teen financial management
- Monzo/Starling: User-friendly banking with spending insights
- Emma/Money Dashboard: Expense tracking and budgeting
- Chip: Automatic saving based on spending patterns
- Plum: AI-assisted saving and investing basics
Online learning resources
- Money Saving Expert’s Teen Cash Class
- The Money Charity’s workshops for young people
- Young Money’s financial education resources
- National Numeracy’s online courses
Setting up digital safeguards
Teach them about:
- Strong, unique passwords for financial accounts
- Two-factor authentication
- Recognising financial scams targeting young people
- Safe online shopping practices
The conversation continues
Financial education isn’t a one-time discussion but an ongoing conversation. Keep communication open by:
Regular check-ins
Schedule monthly “money chats” that feel casual rather than formal. Perhaps during car rides or while cooking together – moments when conversation flows naturally.
Sharing your own journey
Continue being transparent about family financial decisions. When you’re saving for something, share your progress. When you make a financial mistake, discuss it appropriately.
Encouraging questions
Create an environment where no financial question feels stupid. Their curiosity about mortgages, investments, or taxes shows engagement with their financial future.
Building long-term financial resilience
The ultimate goal extends beyond managing a teenage paycheck. You’re building financial resilience that will serve them throughout life:
Emotional money management
Help them recognise emotional spending triggers and develop healthy coping mechanisms that don’t involve shopping.
Financial goal setting
Teach them to set SMART financial goals (Specific, Measurable, Achievable, Relevant, Time-bound) that they can work toward independently.
The value of financial independence
Emphasise that financial independence means choices – career decisions based on passion rather than desperation, the ability to leave unhealthy situations, and the freedom to pursue opportunities.
Conclusion: your lasting impact
Teaching responsible money management isn’t about restricting your teenager’s choices. It’s about expanding them. Give them skills now and watch them build financial confidence that lasts a lifetime.
Remember, every conversation about money, every shared decision, and every supported mistake contributes to raising a financially capable adult. Your teenager’s first job is just the beginning of their financial journey, and with your guidance, it’s a journey toward security, confidence, and success.
The lessons you teach now through patient guidance, practical examples, and continued support become the foundation of their adult financial life. You’re not just teaching them to manage a paycheck, you’re empowering them to build the life they want, make informed decisions, and approach their financial future with confidence rather than fear.
Start today. Have that first conversation. Open that first savings account together. Celebrate that first successfully managed paycheck. Your investment in their financial education pays dividends that last a lifetime.
Resources
[1] – https://maps.org.uk/en/publications/research/2023/uk-children-and-young-peoples-financial-wellbeing-survey-financial-foundations
[2] – https://www.lfbf.org.uk/wp-content/uploads/2024/07/YPMI-report-2023-24.pdf
[3] – https://www.lfbf.org.uk/wp-content/uploads/2024/07/YPMI-report-2023-24.pdf
[4] – https://www.royallondon.com/about-us/media/media-centre/research/
*Collaborative feature post*
How to transfer your e-wallet to your account: Philippines edition
Over the years, an increasing number of parents in the Philippines have used e-wallets for their daily transactions. The Bangko Sentral ng Pilipinas (BSP) noted that the number of accounts for e-wallets in the Philippines reached 393.6 million in 2023, making digital wallets an essential tool for managing family finances and daily expenses. However, one common question busy parents often ask is how to transfer your e-wallet to your account successfully and keep it too!
Below is a practical guide designed specifically for parents, covering everything you need to know about transferring your e-wallet funds and keeping it too!
Everyday transactions and convenience
Are you the type who uses your e-wallet for routine daily transactions, such as paying for a Grab ride or dining out? If so, then you can calculate the total routine transactions demand for the week to determine how much balance you should have in your e-wallet.
Keeping your balance in your Maya wallet to cover just enough for the week, plus a little extra, ensures that you can pay for your daily expenses while also deterring you from making unnecessary large purchases. This can also be a wise way to stay within budget, as spending outside of your routine transactions may leave you short on funds for the rest of the week.
Transaction fees and cash-in options
Depending on your e-wallet, you may be charged a small transaction fee each time you cash out funds from your bank or other accounts to your e-wallet. If you expect to make multiple top-ups over the week or month, consider those fees as well when deciding how much to keep in your e-wallet. However, a more cost-effective approach would be to make a single cash-in transaction every few weeks instead of daily.
Knowing your cash-in options can help you determine how much money to keep in your e-wallet as well. For instance, if you have easy access to reload points such as convenience stores or if your payroll account is linked to your e-wallet, then you may not need to keep such a large balance. Otherwise, if there aren’t any reloading outlets near you, then having a larger wallet balance may be less of a hassle.
Rewards, cashback, and seasonal discounts
Many e-wallets offer various rewards and cashback when you use their services to pay for bills or other transactions. To take advantage of such offers, consider topping up your e-wallet with the amount needed for your bills, in addition to your usual budget, so that you can pay for them digitally instead. Just make sure that you make the payment as soon as possible so that you won’t accidentally spend what should be for your bills on your daily expenses.
If you’re anticipating seasonal discounts such as double-digit or holiday sales, you can also top up your digital wallet in advance for faster transactions. To make sure you don’t spend recklessly, however, set a specific budget to be used for purchases for that particular sales period.
Emergency funds
It’s also important to keep a modest amount in your e-wallet to cover for small emergencies, such as unplanned transport needs or medical costs. This could range from PHP 1,000 to PHP 3,000, or more, depending on your financial means. In addition, having an emergency fund in your own e-wallet can also be beneficial in cases where you need to quickly transfer money to family members, such as when they’re facing an emergency themselves.
Opportunity cost and interest-bearing accounts
Having a large amount just sitting in an e-wallet that doesn’t earn interest can actually be losing you money that you could’ve earned instead. Hence, consider limiting the amount in your e-wallet to your daily expenses and your emergency fund only. Here’s a pro tip: you can put any excess funds in a savings account that earns a higher interest so that it grows over time.
Fortunately, some e-wallets offer their own savings counterparts, allowing you to seamlessly transfer your e-wallet funds to your digital savings account with just a few taps. Maya wallet users, for instance, can maintain their own Maya Savings accounts, which offer higher rates than traditional banks and allow users to reduce transfer fees. With this approach, you can maximise your e-wallet use for daily expenses while growing the rest of your funds in the process.
Security and fraud prevention
While most e-wallets employ top-notch security measures to ensure their users’ funds are safe, it would still be wise to avoid keeping a large balance in your e-wallet to minimise potential losses from hacking or fraudulent transactions.
To better protect your funds, ensure that you activate your e-wallet’s security features, such as two-factor authentication, biometric verification, and spending limits, for an additional layer of protection.
Ultimately, the amount to keep in your e-wallet can depend on multiple factors and varies from individual to individual. The points above should help you determine a good baseline amount to keep in your wallet that covers your expenses while not wasting your money’s potential.
Transfer funds instantly from your e-wallet to your bank account
Transferring funds from your e-wallet to your bank account is a convenient option, especially when managing a family budget or dealing with unexpected expenses. Follow these simple steps to move your funds securely and quickly:
- Log in to your e-wallet app.
- Find the “transfer” option.
- Select your linked bank account or add one if you haven’t already.
- Enter the amount of money you wish to transfer.
- Confirm the details, then click “transfer funds.”
Most transfers occur instantly or within minutes, depending on your e-wallet provider.
How to transfer e-wallet to account using the FNB App
If you’re using FNB eWallet specifically, transferring funds is just as straightforward:
- Open your FNB eWallet app.
- Select “Link eWallet to account via the app.”
- Choose your account and enter your FNB eWallet PIN.
- Enter the amount you wish to transfer.
- Confirm and complete the transaction.
This process is especially handy when balancing family finances or sending money quickly to relatives.
Important security tips for parents
When transferring funds, always:
- Keep your eWallet PIN safe.
- Regularly perform e-wallet balance checks.
- Enable security features like biometric verification or transaction alerts to ensure your funds stay secure.
Frequently Asked Questions (FAQS)
Can you transfer an eWallet to your bank account?
Yes, most ewallet providers allow direct transfer from your ewallet to your bank account.
How to cash out an eWallet?
You can cash out by transferring your ewallet balance to your linked bank account and then withdrawing funds via ATM or bank branch.
Can I transfer TNG eWallet to bank account?
Yes, Touch n Go eWallet supports bank transfers, enabling you to easily transfer funds from your eWallet to your bank.
Is it possible to transfer money from an IRCTC e-wallet to a bank account?
Yes, IRCTC ewallet allows transferring money back to your bank account through their online portal.
How do I withdraw from an eWallet?
Withdraw by transferring your ewallet funds to your linked bank account, then accessing your funds via ATM or bank withdrawal.
Additional quick tips for parents:
- Regularly check your e-wallet balance using your app or the e-wallet balance check number.
- If you’ve forgotten your eWallet card PIN, use the “Forgot eWallet Card PIN” option in your app to reset securely.
- Use QR codes for instant transfers—scan the QR code to make an instant fund transfer now.
Wrapping up
Transferring your ewallet funds to your account shouldn’t be complicated—especially for busy mums managing household budgets and family financial responsibilities. Follow these straightforward tips and frequently asked questions to ensure your ewallet transfers are seamless, secure, and stress-free.
*Collaborative feature post*
How to teach your child financial responsibility
If you have a family and live on a budget, then you will need financial planning to build security. As they get older it’s important that you know how to teach your child financial responsibility. It is never too early to teach kids finances because the earlier they start, the better their relationship with money.
First, you teach your kids about money and how it is earned and then saved. Ultimately you want your children to know how to make money work for them, not the other way around. Here are some ways to teach your child financial responsibility.
How do you explain responsibility to a child?
Your child should learn about responsibility from as young as when they’re toddlers, as it encompasses making good choices and being accountable for their actions. As your child gets older you can specify responsibility, for example, ‘If I make £5, I can either spend it on Robux, invest it in a business idea or put it into my savings accounts. Which is a better choice for me?’
Slowly but surely they will understand their actions will determine how their future will look so being more responsible for their actions will mean better outcomes in their future. These kids savings tips should be coupled with setting an example yourself – so if you’re a big spender, you may not be showing your children how to be frugal.
Why is it important to teach your child responsibility?
As mentioned above, teaching your child early on how to be responsible for their financial future means they are less likely to get into debt, make poor life choices and suffer later in life. Knowledge is power, as they say, and there’s nothing quite like financial education to help your child feel more in control.
How to teach your child financial responsibility
Activities to teach kids responsibility should include games and showing rather than telling. We will go through how to help your child understand money in this article.
How to teach a kid to be responsible – open up the talk about money as soon as possible
As soon as children are old enough to understand that money can be exchanged for goods and services, open up the conversation about how one earns money, i.e. through a job, and then saves or invests that money to further their plans in life. My boys are 10 and 11, and for a few years now I have explained that mum and dad work to receive money which helps us save for the future, including buying a house and a car, as well as investing in our family businesses to grow more wealth.
You don’t have to be super detailed about how it works – that can come in time. The importance here is to open up the conversation and make them aware that money doesn’t grow on trees, nor should it be treated as such. Money should be treated as it is, currency to assist us in improving our future.
How to teach your kids about money – teach your child about money through play
A great way to teach kids about how money works is to introduce games like money maths, which will not only teach them about math calculations but also how money is used. Money maths is also a great way to help children understand the value of the pound by learning to what each currency corresponds.
There are lots of great money games around that you could introduce at home. Money manager games like Monopoly* are a wonderful way to teach kids, not only how to work money maths, but how to save and invest their money into property. During a game talk about what it would mean for them to invest in a property in the future and the kind of return, they would expect.
My ten-year-old is already a Monopoly mogul. He saves all his money until he reaches the two most expensive streets on the board, Park Lane and Mayfair, and then he clears us out by investing in houses and hotels. He has learned quite quickly that saving your money and investing it into something that offers a significant return is the way to maximise chances of earning more money in the long term.
How to teach your child about money – introduce kids to budgeting
Part of getting your children on board with financial savings can be making it a family plan to save and invest, and even having a little fun with it at the same time. You could have different weekly activities that involve saving money that you and your spouse can discuss with your children and make different goals you’d like to see them achieve.
But even during their playtime, there are ways to help them learn such as playing games like the ones listed here. Basically, the sooner you start your children on their financial savings journey, the further ahead they’ll be once they reach their mid-high school and college years. The plan is to keep them out of debt and teach them the responsibility of saving and managing their money before it’s too late.
How to teach kids to be responsible – clear savings jars are king
Even in the digital age, you should still emphasise the importance of cash to kids because it lets them know that money doesn’t grow on trees. Financial expert Dave Ramsey recommends getting your child a savings jar when they’re young and allowing them to see the money grow as they save it. He also suggests making sure it’s not free allowance cash but the money they earn from helping around the house and putting in their share of work because, again, the idea is to make sure they know money must be earned. It also makes it less likely they’ll be tempted to go out and spend it.
How to teach kids about finances – look into a child savings account
Another great way to save money is to find a child savings account that offers compound interest on deposits. Let your child come with you to the bank and deposit their hard-earned cash from their jars into a savings account while the bank manager can teach them all about what happens to their money under the responsibility of the bank.
Show them their monthly bank statements so they can see how their money grows. They will enjoy seeing the value of their bank account increase and the euphoric feeling they get knowing that it is all their money they saved.
How to teach finance to kids – get kids used to paying in cash
While it’s important to use your credit card or debit card as needed and eventually teach children about credit scores, you don’t want them to get the idea that credit cards can be used for everything. Using cash at the register when they’re with you helps them learn they should only buy things within their means. Plus having them hand it to the cashier can also be a teaching moment.
Ways to teach your child responsibility – talk about bad loans and the impact they have on their future
There is of course a time and place where personal loans are important such as student loans, mortgages or business loans. But getting into a habit of borrowing money is not advisable. It’s important when teaching your child financial responsibility, you warn them while they’re still young about predatory loans.
Show them how to avoid high-interest loans like car title loans. Loans are only intended for significant financial needs when your income is steady. And credit cards are not meant to be used at their maximum limit.
How to teach kids financial responsibility – find ways for them to make their own money
Encourage your children to think outside of the box and come up with ideas that can help them make and grow money. Discuss important business lessons like identifying a market need. They could come up with something as simple as creating a product or service and selling it on eBay. The idea is to show them making money can be in their own hands. If they can dream it, they can do it.
How to teach your children responsibility – teach them long-term life lessons
Teaching kids about protection like a retirement plan, life insurance for the family and saving energy which is vital in safeguarding the future of the planet can be massive teachable moments to help them grow as adults. Here are seven ways to teach children about saving energy now so they can save money later:
- Before you start teaching children about how to save energy, it is important to make sure they know where energy comes from. It is worth checking to see whether your children know how your home is heated, what the different types of fuels are, and even how your cooker runs. It is also important to explain to children the impact that excessive energy usage can have on the environment – and their money!
- Explain to children that although leaving appliances on standby is an easy option, it is not the best choice for the family finances or for the environment. Leaving appliances on standby rather than switching them off completely could be costing your family as much as £37 per year. Standby is also increasing our energy usage, which is extremely damaging to the environment.
- If you want to take the ‘standby’ message one step further, make a decision with your family to spend one evening a week with no TV, tablets, phones or computers. Try to turn this into some fun family time by playing games, reading books or perhaps even just chatting!
- An easy way for families to save energy and perhaps some money is to replace regular lightbulbs with energy-saving versions. You could even try to see, with the help of your children, whether there are any lights in the home that you could do without or could replace with more energy-efficient alternatives.
- One of the best ways to save money is to have sufficient insulation in your home. A fun way to get children involved in insulating the home is to ask them to make a draught excluder for their bedroom door or for the front door. Controlling the temperature of your home is especially important in the winter months when people have the heating on. Having the heating on at a consistently low temperature would be better for your pocket and for the environment. One way to control the temperature in your home is to ensure that your central heating system uses an energy-efficient
pump, such as those available from
Pump Sales Direct. Get the children involved in checking and comparing the temperature in different rooms of the house.
- Children are great at coming up with ideas so try holding a family ‘brainstorm’ to see how many ways they can think of saving money in the home.
Financial responsibility for a child is a valuable skill to learn. It will set them up with clear goals for the future and encourage them to plan accordingly. If we can avoid our children getting into debt, then this would be the biggest lesson we can pass on. So, let’s start now!
FAQ
How do I teach my child financial responsibility?
Check out the tips above which should hopefully give you some insight into talking to your child about financial responsibility.
Should I explain my financial situation to my kids?
You should honestly, but appropriately talk to your kids about your financial situation. For example, if you’re in dire straights, balance honesty with caution. You don’t want to burden your child with adult-sized problems, but pretending things are great when they’re not is also not helpful.
Instead of rattling off all the problems you have with debt, try to explain the situation in a relatable way. You could mention that you’re trying to earn more money to pay for bills or that you’d need to work into the budget the item your child wants to see if you can afford it. Involve the kids in the budget too – a great way to do this is to bring a list to the shops and help your child add up the cost of the grocery list to see if they’ve stuck within the budget. If there’s money to spare, they can get that item they want. If there isn’t, they can’t.
Have you got any tips on how to teach your teenager financial responsibility?
Another question asked was, ‘How do I teach my teen financial responsibility?’
“One way to help teenagers take responsibility for their money is to talk to them about your financial responsibilities. Talk to them about your income and what you need to budget for. This includes bills, shopping, and anything you spend on them, such as school lunches or trips.”
https://www.moneyhelper.org.uk/en/family-and-care/talk-money/how-to-help-teenagers-manage-their-money
As a parent what is the best method to teach kids how to spend money?
“Give them a piggy bank or money box for their own cash.
Talk about why it’s important to keep money safe.
Introduce the idea of saving for something they really want.
Together, regularly count the money they’ve saved.”
https://www.moneyhelper.org.uk/en/family-and-care/talk-money/how-to-talk-to-your-children-about-money
What is the best way to teach your child or children how to be successful and secret on making money and saving? The school system is preparing our children for financial hardship and bad financial decisions
Teaching money management in schools is such an important step in helping kids educate financially. But unless the whole education system changes, I doubt subjects like business management, investing/saving money and getting a mortgage will be gracing our kids’ curriculum anytime soon!
How do I teach myself to better manage my money and financial responsibility?
Check out my article here on ‘Money saving for families‘ for more information on how to better manage your money and financial responsibility.
Is it your responsibility to feed your kids?
Yes absolutely. When you became a parent, you signed up to feed your kids.
At what age should parents disclose their financial details to their kids?
Another question asked was, ‘At what age did you start talking to your kids about personal finances? How did it turn out? What would you recommend for other parents?’
As soon as your kids start to take an interest in money and you think they’re old enough to understand how it works, then they’re old enough to start getting a financial education. There isn’t a set age.
How do you make a child pay for something they want in order to learn responsibility when they don’t have a job?
This is a great question! You can start by using an earnings/reward chart and list basic chores around the house from which they could gain some pocket money/allowance. You can then progress to jobs outside the house and a weekly salary to mimic working in a job environment. Advise them to put a percentage of their money into a savings account and they can spend the rest on what they want.
If you could create a public school curriculum that would teach children and adolescents how to achieve financial success and live the lives of their dreams after they graduate what would it look like?
A great answer to this question can be found here: https://qr.ae/pvMLpm
Besides financially how can parents be most conducive to their children’s education?
You can find an answer to this question here: https://qr.ae/pvMLI2
Do you as a parent feel it’s your responsibility to help your grown children financially if they need it?
I prioritise my kids’ health and well-being over anything, and helping them be responsible adults is one way of becoming well-rounded humans. The more knowledgeable they are, the happier they will be in the long run.
How should I financially prepare for parenthood?
I have a great article here about how to prepare for a new baby which will help!
*Collaborative feature post*
*Links marked with a ‘*’ contain affiliate links – I may earn a small commission if you click through to buy – thanks for your support!
How I’m saving for my kids (and myself) with Beanstalk
If you are anything like me, then the thought of doing any kind of financial admin, like sorting out your kids’ child trust funds (CTFs) or even your own ISA is enough to bring on a cold sweat.
Well, thanks to Beanstalk* it need not be so daunting.
I had been putting off getting to grips with my kids’ accounts for years. The hassle of rummaging through paper statements and a clunky online portal meant I wasn’t that aware of how much we had saved for them or what fees were being charged. Plus, it was almost impossible to allow my partner or the grandparents to contribute.
But the onset of the pandemic focused my mind, like I’m sure it has for many families to consider ours and our kids’ money. I also wanted to involve the kids early in the saving process to teach them to look after their money, too.
Enter Beanstalk*!
As a bit of background I set up my older children’s CTFs with OneFamily (or Family Investments as they were known back then) and I had been saving between £10 – £20 a month.
In 2019, my first girl was born. I set up another Junior ISA and during this year I started using apps, like Moneybox, Plum, Chip and Tandem for myself – although I soon forgot that some of them charged a monthly fee – whoops!
In 2021, my second baby girl (4th baby) was born and again I set up a Junior ISA with OneFamily not realising there were other alternatives.
In 2022 I found Beanstalk after being invited to try the app by the co-founder of Beanstalk, Cem Eyi, a father who had gone through a similar experience with OneFamily and wanted to simplify saving and investing for his family in one easy-to-use app – hence Beanstalk was born.
His daughter’s Child Trust Fund was also with OneFamily and after struggling with their interface and the 1.5% annual fee, Cem wanted Beanstalk to be an easier experience for parents.
And it is.
So what is Beanstalk?
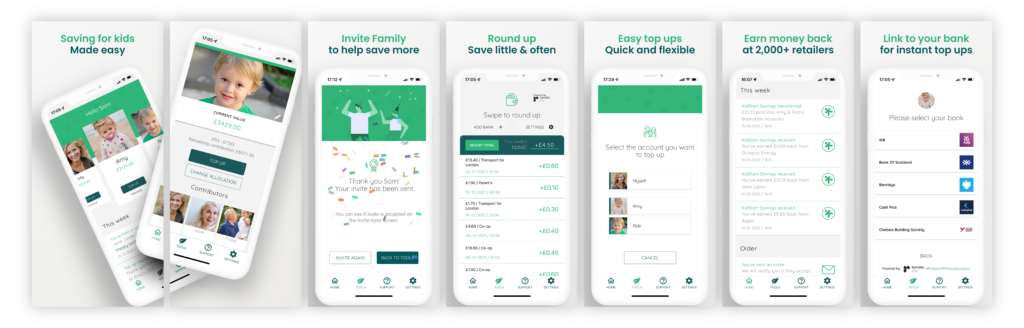
Beanstalk* is a simple app that makes saving for children (and yourself) easy. The app is packed with tools; including money back on purchases and rounding up your change.
I opened my children’s Beanstalk Stocks & Shares Junior ISA and ISA for myself in minutes – handy for a busy mum like me. There are no regular contributions I had to commit to, making it friendly to my sometimes-volatile finances.
Launched by the team behind KidStart, Beanstalk has been helping parents save for their children for over 12 years and has helped thousands of families save millions for their kids. You can join them today by clicking here*. Please remember, your capital is at risk as with any investment the value can go down as well as up.
Is Beanstalk free?
Downloading and using Beanstalk is free with no fixed monthly or minimums fees. There is an annual fee of 0.5% of account value, however, which beats the 1.5% fee charged by some other Child Trust Fund and Junior ISA providers at the moment.
Some of the tools I used to help me save
Beanstalk has some handy tools to help me save little and often. I have found it easy to save on “auto-pilot” using their round up tool, for example. Also, I have invited hubby and extended family to be linked on the app. They can see their contributions and send messages with any gifts, which is nice for the children to see how their family has been saving for them over the years.
I also use their sister app, KidStart*, when shopping online to receive money back on my purchases – for example Sainsbury’s give up to 10% back which goes straight into my kids’ Beanstalk accounts. Conveniently, you can access it directly from the Beanstalk app or use the same credentials to log into the KidStart website or app.
What did I think of Beanstalk?
I found the Beanstalk app* very simple to use and I’ve pretty much used all the other apps in the online banking app space. Where Beanstalk stands out is that I’m saving for my ISA as well as the kids’ Junior ISAs and it’s all in one place, in front of your face.
With other platforms, I had to log onto the PC and check my account details, statements, and documents. It was overwhelming. What am I saving with? What are the fees? Where am I supposed to go to find out how much I’ve saved? With Beanstalk, it’s in one easy-to-use app, all in one place and you can share and invite people to contribute in just a few clicks of a button.
I found the information on the app valuable because I’m coming from a newbie standpoint and learning about the basics so that I can teach my kids to save and invest too. So having those kinds of tools available to me is vital.
We need to teach our kids to save what they can, when they can. They need to learn how to make their money work harder for them. This is the aim of Beanstalk, and my aim too.
Sign up to Beanstalk here and make savings simple for you and your family!*
This is a paid collaborative post with Beanstalk. As always with investments, your capital is at risk. The value of your investment can go down and up, and you may get back less than you invest. This information should not be regarded as financial advice. Links marked with a ‘*’ are affiliate links, which means I may mean earn a small commission at no extra cost to you when you click through and buy. Capital at Risk. See Beanstalk’s website for more details.